- Faculty
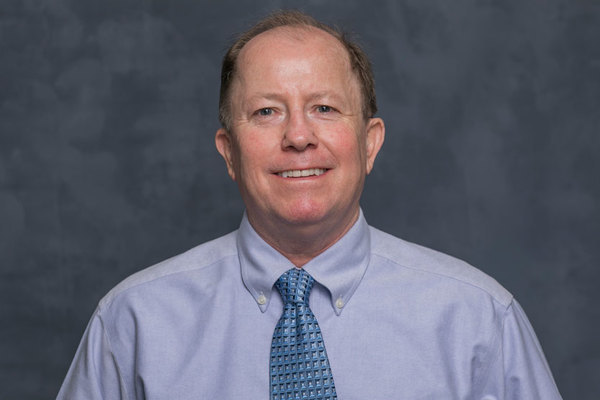
Robert A. Jarrow
- Ronald P. and Susan E. Lynch Professor of Investment Management
- Co-Editor, Frontiers of Mathematical Finance
- IAFE Senior Fellow, International Association of Financial Engineers
Biography
Robert Jarrow is the Ronald P. and Susan E. Lynch Professor of Investment Management at the Cornell SC Johnson College of Business. He is a co-creator of the Heath-Jarrow-Morton model, the reduced form credit risk model and the forward price martingale measure, which are standard frameworks for pricing and hedging derivatives in major financial institutions. He was the first to distinguish forward and futures prices and to analyze market manipulation using arbitrage-pricing theory. He has written seven textbooks, including the first on the Black Scholes Merton and Heath Jarrow Morton models, and has published more than 250 academic journal articles.
Jarrow co-created the journals Mathematical Finance and Frontiers of Mathematical Finance and serves on advisory boards for numerous academic journals. His research has earned many awards, including the Graham and Dodd Scrolls Award in 2001, the CBOE Pomerance Prize in 1982, the Ross Best Paper Award in 2008 and the Bernstein Fabozzi/Jacobs Levy Award in 2009. In 1997, he was named IAFE Financial Engineer of the Year, and he is an IAFE senior fellow. He is a member of the Fixed Income Analysts Society Hall of Fame and Risk Magazine’s Hall of Fame, and is listed in Who’s Who in Economics. He received Risk Magazine’s Lifetime Achievement Award in 2009.
He has served on various industry advisory boards and has consulted for the Federal Deposit Insurance Corporation, the U.S. Treasury Department, the Federal Reserve Bank of New York and numerous hedge funds and commercial and investment banks.
Education
PhD Massachusetts Institute of Technology, 1979 MBA Amos Tuck School of Business, Dartmouth College, 1976 BA Duke University, 1974
Research
- Wu, David; Jarrow, Robert. "The Treasury - SOFR Swap Spread Puzzle Explained"Quarterly Journal of Finance. 15.4 (2025): e2650001
- Jarrow, Robert. "Do Bubbles Exist? Positive Digital Asset Market Prices are the Definitive Proof"Journal of Investment Management. 24.1 (2026)
- Jarrow, Robert. "Digital Assets, Bubbles, and Derivative Prices"Review of Derivatives Research. 28.3 (2025): 13
- Jarrow, Robert. "Optimal Strategies for Digital Assets with No Fundamental Value"Journal of Portfolio Management. 52.1 (2025): 44 - 51
- Grigorian, Karen; Jarrow, Robert. "Filtration Reduction and Completeness in Brownian Motion Models"Frontiers of Mathematical Finance. 5 (2025): 94-120
- Grigorian, Karen; Jarrow, Robert. "No Arbitrage for a Special Class of Filtration Expansions"Annals of Finance. 21 (2025): 45-68
- Hilscher, Jens; Jarrow, Robert; van Deventer, Donald. "The Valuation of Corporate Coupon Bonds"Journal of Financial and Quantitative Analysis. 60.5 (2025): 2259 - 2292
- Fusari, Nicola; Jarrow, Robert; Lamichhane, Sujan. "Testing for Asset Price Bubbles Using Options Data"Journal of Business and Economic Statistics. 43.4 (2025): 807-821
- Jarrow, Robert. "A Credit Spread Decomposition: A Resolution of the Credit Spread Puzzle"Quarterly Journal of Finance. 14.4 (2024): 2450016
- Jarrow, Robert. "Arbitrage Pricing Theory 50 Years after Black Merton Scholes"Journal of Investment Management. 22.4 (2024)
Awards
- IAFE/SunGard Financial Engineer of the Year (1997)
- Fixed Income Analysts Society (FIASI) Hall of Fame (2004) Fixed Income Analysts Society
- Member Risk Magazine's 50 member Hall of Fame (1900) Member Risk Magazine