Expanding financial services in emerging markets, why local context is a moat
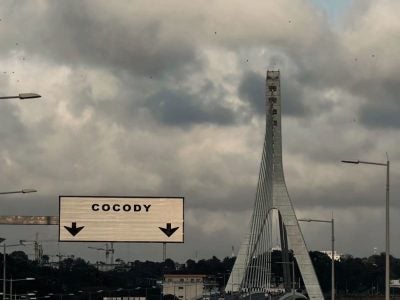
During a 10-week research engagement in Abidjan, supported by the Cañizares Center for Emerging Markets, I worked with UseRank, a Y Combinator-backed community finance startup, to develop a go-to-market strategy for Francophone West Africa.
The assignment appeared straightforward: How do you take a savings product built for one market and introduce it into another?
But conversations with founders, investors and development finance professionals across Côte d’Ivoire revealed a harder question: What does it take to earn trust and navigate the institutions necessary to operate in a new market?
Abidjan sits within the West African Economic and Monetary Union, or UEMOA, a group of eight countries that share a currency and central bank. That alignment creates a natural advantage for regional expansion. But a common monetary framework does not eliminate operational barriers. Financial activities face different authorization requirements, and the ability to distribute products or move money across borders depends on far more than a shared currency.
The gap between regional integration on paper and the realities of operating across markets became the through-line of my summer.
Regulation and adoption must move together
That insight became clearer through conversations with people navigating these tensions firsthand.
I met Aissatou, chief of staff to the CEO of Djamo, a Y Combinator-backed digital financial services company founded in Côte d’Ivoire. Djamo’s early proposition was simple: give people access to a Visa card through a mobile phone.
Historically, obtaining a conventional bank card could require opening an account in person and meeting salary requirements that excluded many prospective customers. Djamo reduced that friction. Aissatou shared a striking early finding: 60% of its initial users had never held a payment card, revealing a large population underserved by the formal financial system.
What interested me was not only the product but also the company’s regulatory journey. Djamo pursued microfinance authorization for years before Djamo Finances received approval in 2025.
Its experience demonstrated that customer adoption and regulatory legitimacy are separate challenges that must be managed together. An accessible product can bring new customers into the financial system, but scaling also requires the institutional permissions to serve them.
Choosing where to compete
Mathias Léopoldie, co-founder and CEO of Julaya, reinforced another lesson: A large market is not necessarily the best entry point.
Julaya builds digital account and payment infrastructure for African enterprises. Mathias explained that competing head-on with consumer players such as Wave, whose pricing helped reset expectations for retail financial services, would have been a punishing contest. Instead, Julaya focused on corporate customers with complex payment needs, compliance obligations and working capital requirements that consumer-first products often do not address.
Its strategy illustrated the value of choosing a segment where a company can solve an important problem and develop a defensible advantage.
Julaya also invested in its own payment infrastructure rather than relying entirely on bank and telecom gateways. The Central Bank of West African States, or BCEAO, launched its interoperable instant-payment platform, PI-SPI, in September 2025, but shared infrastructure does not immediately remove every integration challenge.
That raised another question for me: Which capabilities should a company own, and which can it expect the ecosystem to provide?
A market-entry strategy has to reflect what the ecosystem can reliably deliver today, not just what it promises for tomorrow.
Relationships are part of the infrastructure
To better understand the broader forces shaping these choices, I spoke with Alex Gbetie, who works on a GIZ program supporting financial-sector reform through government engagement, public-private dialogue and capacity building for entrepreneurs.
Our conversation helped explain Côte d’Ivoire’s position as a major commercial hub. Its historical role in French West Africa, relative political stability since 2011, cocoa exports, transport infrastructure and international organizations have reinforced one another over time.
But Alex also reminded me that monetary integration does not erase linguistic, historical and commercial boundaries. Language, business networks and institutional relationships shape whom companies can reach and where trust develops. A regional market can be integrated on paper without being homogeneous in practice.
These conversations changed how I thought about the “phygital” market-entry thesis I had brought to UseRank. I initially viewed physical touchpoints as a complement to a digital product, a channel for onboarding or customer acquisition.
In Abidjan, I began to see human relationships differently. They are part of the infrastructure through which credibility is established, partnerships are built and customer behavior is understood.
For UseRank, that meant looking beyond sign-ups as the primary measure of progress. We needed to understand whether the right customers trusted the product, found it useful and had a reason to return. Acquisition could indicate interest, but sustained engagement provided stronger evidence of value.
The goal was not maximum exposure. It was lasting use.
I arrived in Abidjan expecting to learn how a business playbook crosses a border. I left understanding that expansion begins by asking which assumptions travel, which fail in a new institutional setting, and which must be rebuilt through local relationships.
Silicon Valley will continue to shape many technological and business playbooks. But their success elsewhere depends on how intelligently they are adapted. Francophone West Africa has its own institutional architecture, competitive dynamics and commercial logic.
The moat, I came to understand, is not simply knowing the market. It is translating that knowledge into the right sequence of product decisions, regulatory readiness, partnerships, infrastructure and trust.
I am grateful to the Cañizares Center for Emerging Markets, the Emerging Markets Institute and the Cañizares Fund for making this immersion possible, and to everyone in Abidjan who generously was available for my questions.
About the author
Ayobamigbe Teriba is a 2027 MBA candidate at the Cornell Samuel Curtis Johnson Graduate School of Management focused on emerging markets and sustainable global enterprise. He is particularly interested in go-to-market strategy, business expansion, revenue operations and growth. Before the Johnson School, he worked across Nigeria, South Africa and the Netherlands, investing capital through instruments including syndicate financing, venture capital and sovereign-backed impact investing.
In this article
Article Information
- Categories
-
- Blog Posts